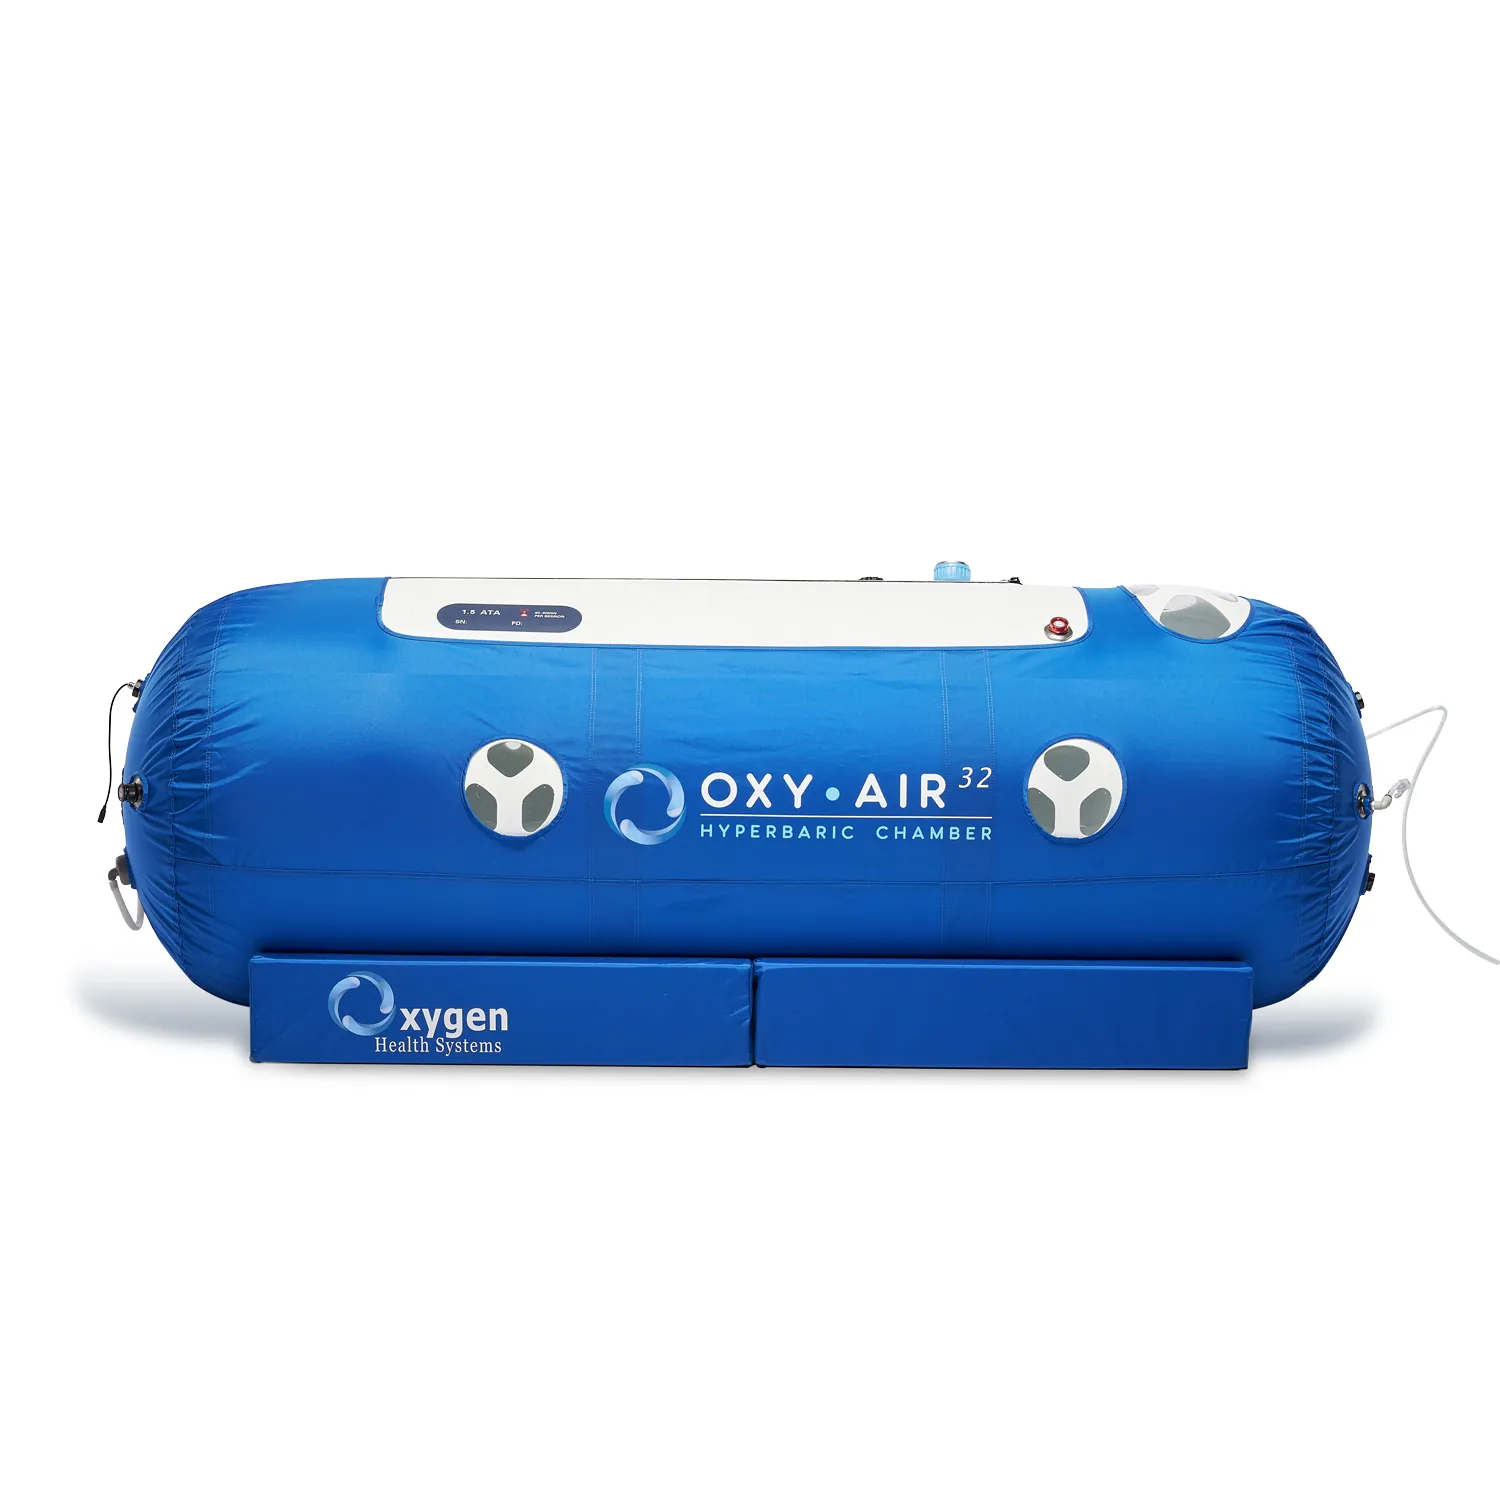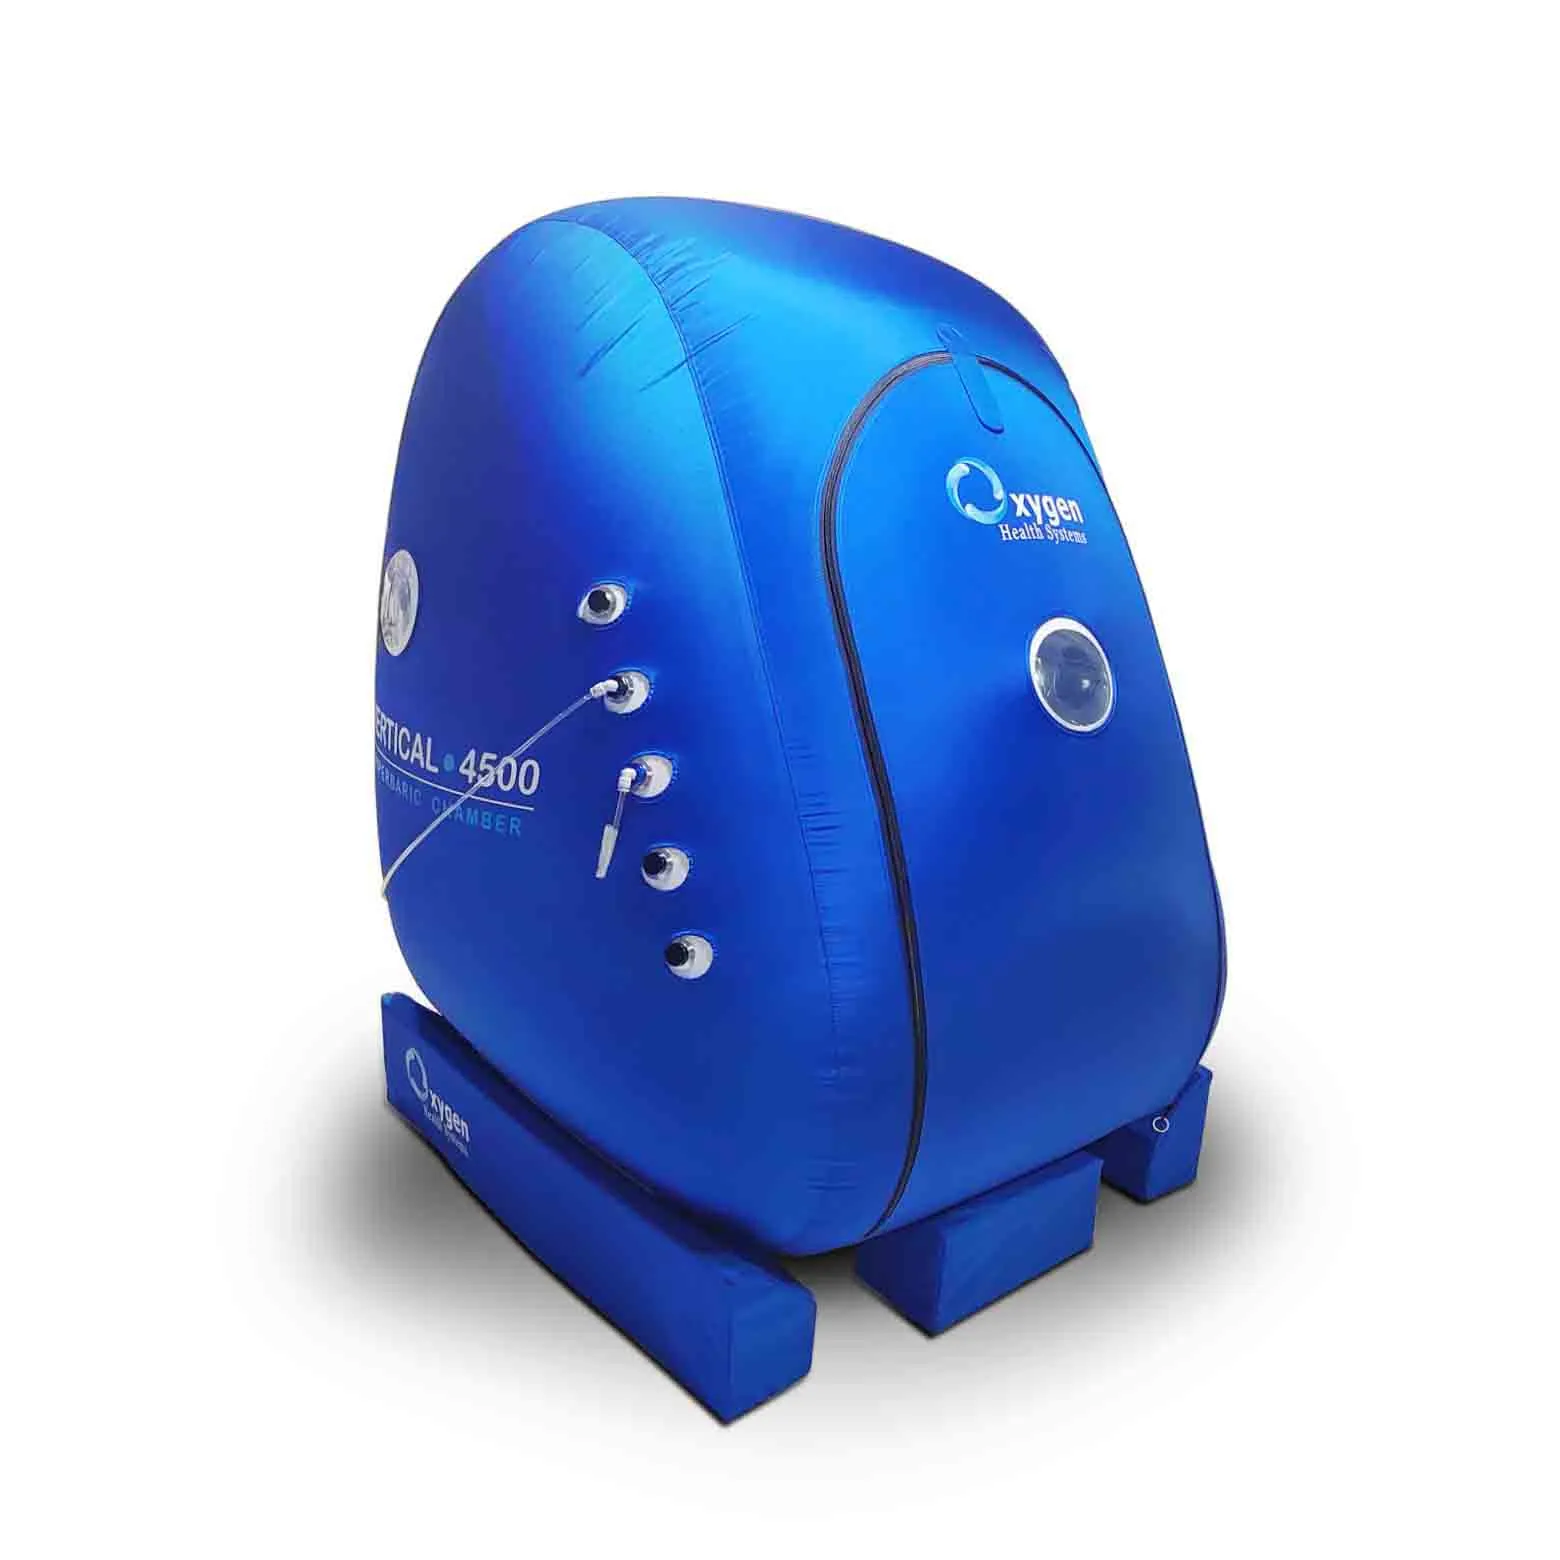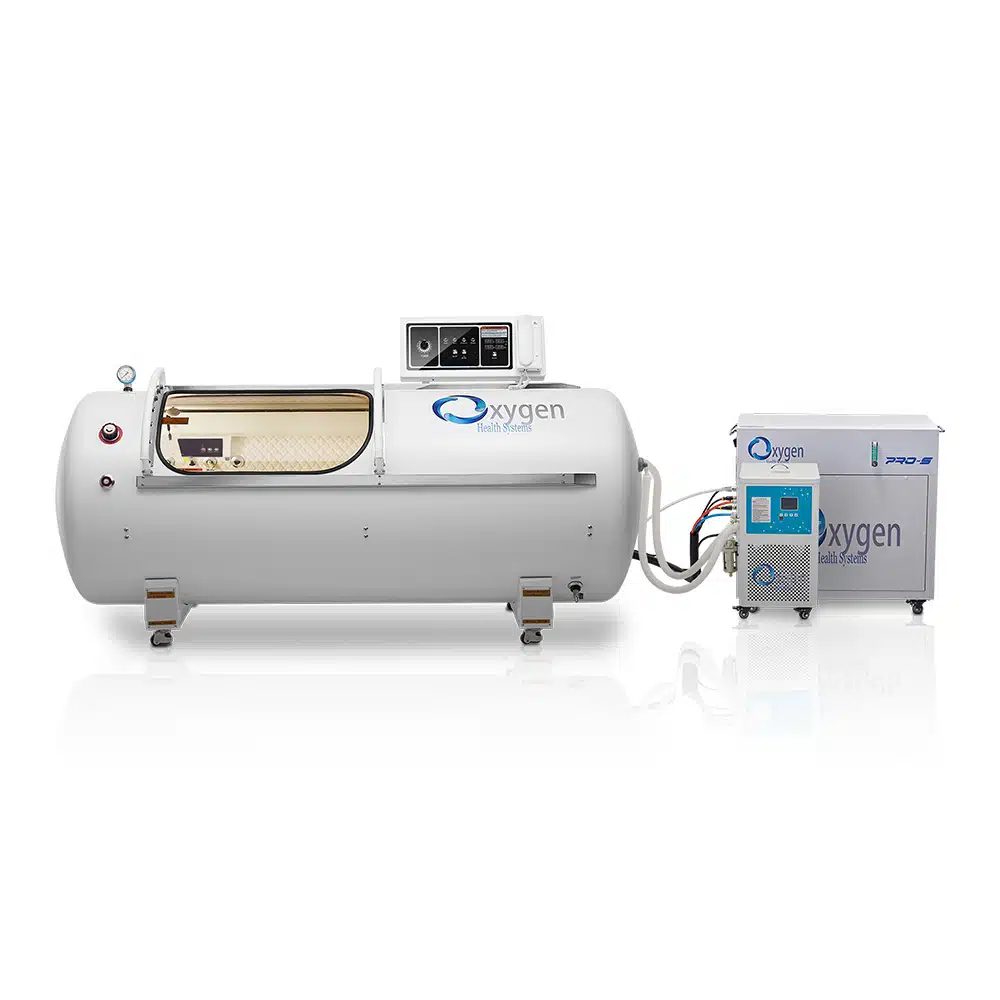
Hyperbaric Oxygen Chambers
How To Use Section 179 To Buy A Hyperbaric Chamber
Aug
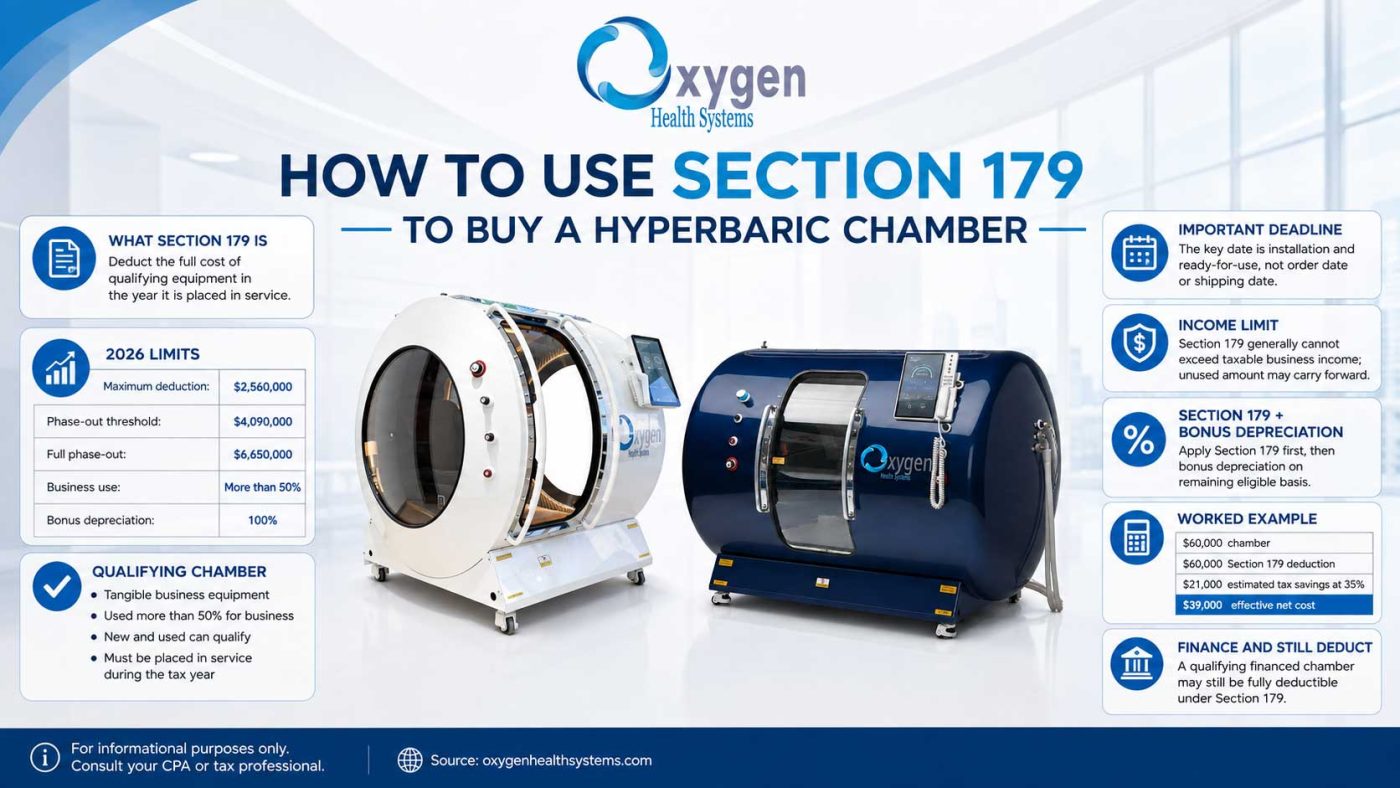
If you buy a hyperbaric chamber for your clinic, wellness center or practice and put it into service before December 31, you may be able to deduct the entire purchase price from this year’s taxable income rather than writing it off gradually over several years. That is Section 179, and for 2026 it covers equipment purchases up to $2,560,000. Almost every hyperbaric chamber on the market sits comfortably below that ceiling, which means the full cost is usually deductible in year one.
Here is how the rule works, what your chamber needs to qualify, and the deadline that decides whether you claim it this year or next.
What Section 179 Actually Is
Ordinarily, when a business buys equipment, the IRS makes you spread the deduction across the asset’s useful life. Buy a $60,000 chamber and you might deduct a fraction of it each year for five or seven years.
Section 179 lets you skip that. You elect to expense the whole qualifying purchase in the year the equipment is placed in service, and the deduction comes off your taxable income immediately.
The practical effect is on cash flow. Instead of waiting years to recover the tax benefit of a purchase you have already paid for, you take it now, in the same year the money left your account.
The 2026 Limits
The One Big Beautiful Bill Act raised the Section 179 ceiling substantially and, importantly, made the higher figures a permanent part of the tax code with annual inflation adjustments. The old $1,250,000 cap is gone.
| 2026 Figure | |
| Maximum deduction | $2,560,000 |
| Phase-out threshold | $4,090,000 |
| Full phase-out | $6,650,000 |
| Business use requirement | More than 50% |
| Bonus depreciation | 100% |
Above $4,090,000 in total equipment purchases for the year, your maximum Section 179 deduction reduces dollar for dollar. At $6,650,000 it disappears entirely.
For context, that phase-out threshold is more than forty times the price of most clinical hyperbaric chambers. Unless you are buying a great deal of other equipment in the same year, it will not affect you.
Does A Hyperbaric Chamber Qualify?
Yes, provided it meets the standard tests the IRS applies to any business equipment.
- It must be tangible business property. A hyperbaric chamber is straightforwardly that.
- It must be used more than 50% for business. This is the test that matters most for chamber buyers, and it is where the line falls between a clinic purchase and a personal one. If you are charging clients for sessions, running a membership program, or offering HBOT as part of a treatment plan, you are on the right side of it. If the chamber lives in your house and you use it yourself most of the time, you are not.
- Where use is split, the deduction is limited to the business use percentage. A chamber used 70% for paying clients and 30% by the owner generally supports a deduction on 70% of the cost.
- New and used both qualify. Section 179 is not restricted to new equipment. A used chamber qualifies as long as it is new to your business.
- It must be placed in service during the tax year. More on this below, because it catches people out.
Clinics, med spas, physical therapy practices, chiropractic offices, sports recovery facilities, and wellness centers charging for sessions all typically qualify. Most business structures work, including sole proprietorships, S corporations and LLCs, subject to the income rules covered below.
The Deadline Is About Installation, Not Purchase
This is the single most common mistake, and it is worth being precise about.
Section 179 applies in the year the equipment is placed in service. Not the year you signed the purchase order. Not the year you paid the deposit. Not the year it shipped. The year it was installed and ready for use in your business.
For a calendar-year business, that means a chamber ordered in November but not installed until January is a next-year deduction, no matter when the invoice was dated.
Hyperbaric chambers are not next-day items. Between manufacturing, delivery, site preparation and installation, the lead time is real. If you intend to claim the deduction for the 2026 tax year, work backward from December 31 and give yourself room. Our team can confirm current lead times and installation windows for any model in our hyperbaric chamber range so you can plan the timing properly.
The Income Limit Most Articles Skip
Section 179 cannot exceed your taxable income from the active conduct of your trade or business. If your practice made $40,000 in taxable income this year and you buy a $60,000 chamber, you cannot deduct the full $60,000 against that income.
The good news is that the disallowed portion is not lost. It generally carries forward to future tax years.
This is also where bonus depreciation becomes useful, because it works differently.
How Section 179 And Bonus Depreciation Work Together
These two provisions are often confused. They are separate tools and they stack.
Section 179 has a dollar cap, requires an election, and is limited by your business taxable income.
Bonus depreciation has no overall dollar cap and can create or increase a net operating loss. It has been restored to 100% for qualified property acquired and placed in service after January 19, 2025, and made permanent.
The IRS requires you to apply them in order: Section 179 first, then bonus depreciation on whatever eligible basis remains, then standard depreciation. In practice, most chamber purchases are fully covered by Section 179 alone. Bonus depreciation matters when the income limit bites or when you are buying at a scale that exceeds the cap.
A Worked Example
A wellness center buys a hyperbaric chamber for $60,000 and has it installed and operating in October 2026. The business has $150,000 in taxable income and a combined federal and state tax rate of 35%.
| Chamber purchase price | $60,000 |
| Section 179 deduction | $60,000 |
| Estimated tax savings at 35% | $21,000 |
| Effective net cost | $39,000 |
The chamber cost $60,000 but the after-tax cost is closer to $39,000. Meanwhile the chamber is already generating session revenue from October onward.
This is a simplified illustration. Your actual rate, entity structure, state conformity and income position all change the arithmetic, which is why the next section matters.
You Can Finance And Still Deduct The Full Price
This is the part that surprises most buyers.
Section 179 applies to the full purchase price of qualifying equipment even when you finance it. You are not limited to deducting what you paid down this year.
So a practice that finances a chamber, puts down a modest deposit and begins monthly payments can still elect to deduct the entire purchase price in the year the chamber is placed in service, assuming the other tests are met. In some cases the first-year tax saving exceeds the total payments made that year.
That combination, monthly payments plus an immediate full deduction, is why so many equipment purchases get finalized in the fourth quarter.
What Your CPA Will Want
Section 179 is elected, not automatic. It is claimed on IRS Form 4562, Part I. Poor documentation is one of the more common triggers for scrutiny, so keep the following together:
- The purchase invoice showing the full price and date
- Delivery and shipping documentation
- Installation records confirming the date the chamber became operational
- Technical specifications for the model
- Records supporting your business use percentage, particularly if the chamber has any personal use
- Financing agreements, if applicable
We can provide invoices, installation certificates, shipping documents and full specifications for your accountant on request.
Two Things To Check With Your Accountant
State conformity. Many states do not follow federal Section 179 rules in full. Your federal deduction and your state deduction may differ, sometimes significantly. This is state-specific and worth confirming before you rely on a number.
Whether Section 179 is even the right choice. Immediate expensing is not always optimal. If you expect to be in a higher tax bracket in future years, spreading the deduction may be worth more overall. Your CPA can model both.
Frequently Asked Questions
Can I claim Section 179 on a chamber for home use?
Generally no. The more than 50% business use test is the deciding factor, and a chamber used mainly by you and your family at home will not meet it. If you are buying for personal health reasons, look instead at whether the purchase qualifies as a medical expense, which is a different set of rules and typically requires a prescription or Letter of Medical Necessity.
Does a used chamber qualify?
Yes. Section 179 covers both new and used equipment, provided the equipment is new to your business.
What if my chamber costs more than my business income?
You can deduct up to your taxable business income, and the remainder generally carries forward to future years. Bonus depreciation may be able to absorb some of the balance, since it is not subject to the same income limitation.
Do I have to use the chamber before December 31?
It has to be placed in service, meaning installed and ready for use in your business, by the end of your tax year. For calendar-year filers that is December 31.
Is there a minimum purchase price?
No. There is a maximum, not a minimum, so chambers at every price point in our range qualify.
Planning A Purchase This Year
The deduction is generous, the limits are now permanent, and the qualifying rules for a clinical hyperbaric chamber are straightforward. The variable you actually control is timing.
If you want the deduction on your 2026 return, the chamber needs to be selected, delivered and installed before December 31. Speak to a specialist about current models, lead times and financing options and we will help you map the timeline backward from your filing deadline.
This article is general information, not tax advice. Section 179 eligibility depends on your entity structure, taxable income, state of operation and how the equipment is used. Confirm your position with a qualified CPA or tax professional before making a purchase decision. IRS Publication 946 is the primary federal reference.